If you have heard about Bitcoin, Ethereum, NFTs, Web3, or cryptocurrency, you have probably come across the word blockchain. The problem is that blockchain is often explained with complicated technical terms that make it sound much harder than it really is.
When I first started learning about blockchain, I made the same mistake many beginners make: I thought blockchain and cryptocurrency were basically the same thing. They are not.
Cryptocurrency is one application of blockchain technology. Blockchain itself is a type of technology that can be used for recording and verifying information without relying on one central database owner.
A simple way to think about it is this: imagine a digital record book that is shared among thousands of computers. New records are added according to specific rules, and once information has been recorded, changing old records can be extremely difficult.
That basic idea is behind many blockchain networks.
This guide explains what blockchain technology is, how it works, how transactions are verified, why blockchain is considered secure, and where it is actually useful.
What Is Blockchain Technology?
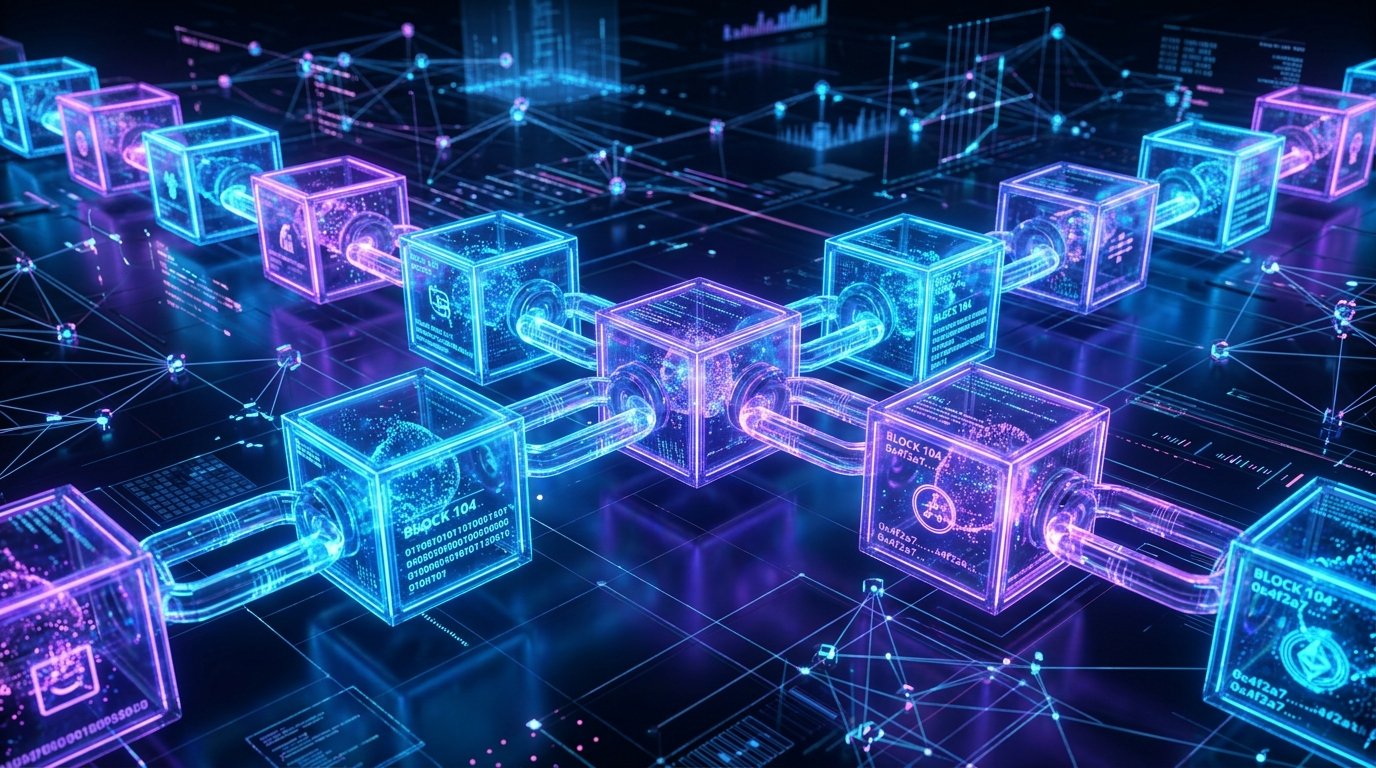
Blockchain is a type of distributed ledger technology (DLT) that stores information in groups called blocks.
These blocks are connected together in a chronological chain. That is where the name “blockchain” comes from.
Instead of keeping a single copy of a database on one company’s server, a public blockchain can maintain copies across many computers, often called nodes.
For example, imagine that Alice sends 1 Bitcoin to Bob.
A traditional payment system might work like this:
Alice → Bank/Payment Processor → Bob
The bank maintains the records and verifies whether Alice has enough money.
With a public blockchain such as Bitcoin, the transaction is broadcast to the network. Participating computers verify it according to the network’s rules, and eventually the transaction is included in a block.
The blockchain then provides a shared record of what happened.
This does not mean blockchain is completely anonymous, magical, or impossible to attack. Those are common misconceptions. Different blockchains have different designs, security models, fees, speeds, and levels of decentralization.
Blockchain vs. Cryptocurrency: Are They the Same?
This was one of the first concepts I had to understand.
Blockchain is the underlying technology. Cryptocurrency is one use of that technology.
Think about it like this:
- Blockchain = the technology
- Bitcoin = a cryptocurrency that uses blockchain
- Ethereum = a blockchain network that supports cryptocurrency and programmable applications
- Smart contracts = programs that can run on certain blockchain networks
You can have blockchain applications that are not directly related to buying or selling cryptocurrency.
For example, blockchain technology can potentially be used for tracking products through a supply chain, verifying digital records, managing certain financial processes, and creating systems where multiple organizations need to share records without giving one organization complete control.
How Does Blockchain Work?
Although the technology underneath can become highly technical, the basic process is easier to understand.
Let’s walk through a simplified blockchain transaction.
Step 1: Someone Creates a Transaction
Suppose you use a cryptocurrency wallet on your smartphone or computer to send digital assets to another wallet.
You enter:
- The recipient’s wallet address
- The amount
- The network
- Any applicable transaction fee
Your wallet creates a transaction and signs it using your private key.
The private key is extremely important. It is what allows the wallet to prove that you are authorized to spend the assets associated with that address.
Step 2: The Transaction Is Broadcast
The transaction is sent to the blockchain network.
Other computers participating in the network receive the transaction and check whether it follows the rules.
For example, the network may check whether:
- The transaction has a valid digital signature
- The sender is authorized to spend the assets
- The transaction follows the network’s format
- The same funds have not already been spent
If the transaction fails the network’s rules, it will not be accepted as a valid transaction.
Step 3: Valid Transactions Are Grouped Into a Block
Valid transactions can be collected into a block.
A block generally contains transaction information along with technical information connecting it to previous blocks.
The exact structure differs between blockchain networks.
Step 4: The Network Reaches Agreement
This is where consensus mechanisms become important.
Blockchain networks need a way for participating computers to agree about which transactions are valid and what the current state of the ledger should be.
Two well-known approaches are:
Proof of Work (PoW)
Bitcoin uses Proof of Work. Specialized computers compete to solve computational problems as part of the process of adding blocks.
Proof of Stake (PoS)
Many modern blockchain networks use Proof of Stake or variations of it. Participants typically lock or “stake” cryptocurrency to help secure the network and validate transactions according to the protocol’s rules.
These systems work differently, and neither should simply be described as universally “better.” Each has different trade-offs involving security, energy use, decentralization, hardware requirements, and economic incentives.
Step 5: The Block Becomes Part of the Chain
Once a block has been accepted by the network, it becomes connected to previous blocks.
The result is a chronological chain of records.
This structure makes unauthorized changes difficult because altering historical information can affect the cryptographic relationships between blocks and may conflict with the copies and rules maintained across the network.
What Is Inside a Blockchain Block?
A block isn’t simply a digital folder containing transactions.
Depending on the blockchain, a block can contain information such as:
- Transaction data
- A timestamp or related block metadata
- A reference to the previous block
- A cryptographic hash
- Consensus-related information
- Other network-specific data
What Is a Hash?
A hash is a fixed-length output generated from input data using a cryptographic hashing function.
You can think of it as a digital fingerprint.
If the input changes, even slightly, the resulting hash can change significantly.
For example, imagine a block has a particular hash:
A81F...29C
If someone changes information contained in that block, the calculated hash would no longer match the original value.
This is one of the reasons cryptographic hashing is important to blockchain systems.
However, hashing alone does not make a blockchain secure. Blockchain security comes from multiple components working together, including cryptography, consensus mechanisms, network design, incentives, and validation rules.
Why Is Blockchain Considered Secure?
Blockchain security is often misunderstood.
People sometimes say, “Blockchain cannot be hacked.”
That is too broad.
Blockchain networks can have vulnerabilities, and cryptocurrency users can lose assets through phishing, stolen private keys, malicious applications, smart-contract bugs, exchange breaches, and other attacks.
The important point is that properly designed blockchain networks can make unauthorized modification of the shared ledger difficult.
Several mechanisms contribute to this.
Cryptography
Digital signatures help prove that a transaction was authorized by the holder of the relevant private key.
Distributed Copies
A public blockchain can have many participating nodes maintaining and verifying copies or portions of the network’s data.
There is no single database server that necessarily controls the entire network.
Consensus
Consensus rules help participants agree on valid transactions and the state of the blockchain.
Linked Blocks
Blocks contain cryptographic references that connect them to previous blocks, making historical modification more difficult.
A Simple Real-World Example of Blockchain
Let’s say a company sells expensive electronics.
The product might pass through several stages:
Manufacturer → Warehouse → Distributor → Retailer → Customer
Normally, each company may maintain its own records.
If there is a dispute, employees may need to compare invoices, databases, shipping documents, and timestamps.
A blockchain-based system could potentially provide a shared record where participating organizations can record specific events.
For example:
- Manufacturer records production information.
- Warehouse records receipt.
- Distributor records shipment.
- Retailer records delivery.
- Customer or auditor verifies relevant information.
This doesn’t automatically make every piece of information truthful. If someone enters false information at the beginning, blockchain does not magically detect the lie.
That’s an important limitation.
Blockchain is better at helping preserve and share records than proving that the original information was truthful.
Where Is Blockchain Used?
Blockchain has applications beyond cryptocurrency.
1. Cryptocurrency
This is the most well-known use.
Bitcoin uses blockchain to maintain a public transaction history without relying on a traditional bank to operate the ledger.
Other blockchain networks support their own cryptocurrencies and applications.
2. Smart Contracts
Some blockchain networks support smart contracts.
A smart contract is essentially a program deployed on a blockchain that can execute predefined logic.
For example, a simple smart contract could be designed to release a digital asset when specified conditions are met.
Smart contracts are commonly associated with decentralized applications, or dApps.
They are powerful, but they are not automatically safe. A coding error in a smart contract can potentially cause serious problems.
3. Supply Chain Tracking
Companies can use blockchain-based systems to record events throughout a supply chain.
The potential benefit is easier sharing and auditing of records among multiple parties.
However, implementation costs, privacy, data accuracy, and integration with existing systems can be major challenges.
4. Digital Ownership
Blockchain networks can be used to create digital tokens representing ownership or rights.
NFTs are one example.
Although NFTs became widely associated with digital artwork, the underlying concept can potentially be applied to tickets, memberships, digital collectibles, gaming items, and other forms of digital representation.
5. Financial Services
Banks and financial institutions have experimented with blockchain and related distributed-ledger technologies for areas such as settlement, tokenization, cross-border transactions, and record management.
Not every blockchain idea makes financial processes cheaper or faster, but the technology can be useful when multiple parties need to coordinate shared records.
What Do You Need to Use Blockchain?
You don’t need an expensive computer to learn blockchain.
A normal setup is enough:
- Windows PC or Mac
- Android phone or iPhone
- Modern web browser such as Chrome, Edge, Firefox, or Safari
- Internet connection
- A cryptocurrency wallet for networks you want to explore
- A blockchain explorer for viewing public transactions
If you’re just learning, I recommend starting with small amounts or test networks rather than immediately putting significant money into cryptocurrency.
You can learn a surprising amount simply by viewing transactions on a blockchain explorer and following how they move through the network.
How to Explore a Blockchain as a Beginner
Here’s a simple learning exercise I found useful.
Step 1: Choose a Blockchain
Start with a well-documented public blockchain such as Bitcoin or Ethereum.
Step 2: Open a Blockchain Explorer
A blockchain explorer lets you search public information such as wallet addresses, transactions, blocks, and confirmations.
You don’t need to own cryptocurrency to explore many public blockchain records.
Step 3: Search for a Transaction
Enter a transaction ID into the explorer.
You may see information such as:
- Transaction status
- Block number
- Amount transferred
- Sender and recipient addresses
- Transaction fee
- Confirmation information
Step 4: Examine the Block
Look at the block containing the transaction.
You’ll begin to see how individual transactions become part of a larger chain of blocks.
This hands-on approach is much easier than reading technical definitions for hours.
Common Blockchain Mistakes Beginners Make
I’ve noticed that most beginners struggle with the same few misconceptions.
Mistake 1: Thinking Blockchain Means Bitcoin
Bitcoin uses blockchain, but blockchain isn’t Bitcoin.
Blockchain technology can be used in many different systems.
Mistake 2: Assuming Blockchain Is Completely Anonymous
Public blockchains can provide pseudonymous addresses rather than traditional names.
Transactions may be publicly visible, and blockchain analysis can sometimes connect addresses to real-world identities.
Never assume that using cryptocurrency automatically makes your financial activity invisible.
Mistake 3: Believing Every Blockchain Is Decentralized
The word “blockchain” doesn’t automatically tell you how decentralized a network is.
You need to examine who operates nodes, who controls development, how consensus works, how validators are distributed, and other network characteristics.
Mistake 4: Thinking Blockchain Makes Bad Data Correct
If incorrect information is recorded, blockchain doesn’t automatically know that it’s false.
The technology can protect the integrity of recorded data, but it cannot guarantee the accuracy of information entered into the system.
Mistake 5: Ignoring Wallet Security
For cryptocurrency users, wallet security is critical.
Never casually share your private key or recovery phrase.
Be especially careful with:
- Fake wallet websites
- Phishing emails
- Suspicious browser extensions
- Fake customer-support accounts
- Unknown links
- Malicious applications
A legitimate-looking website can still be designed to steal your wallet credentials.
Blockchain’s Limitations
Blockchain isn’t the perfect solution for every problem.
There are several practical limitations.
Scalability
Some networks can experience congestion when demand becomes high.
This can increase transaction fees or processing times.
Complexity
Blockchain systems can be difficult for ordinary users to understand.
Wallet addresses, private keys, gas fees, confirmations, bridges, smart contracts, and network selections can be confusing at first.
Energy Consumption
Some blockchain networks using Proof of Work require significant computational resources.
Other networks use Proof of Stake or different mechanisms with different resource requirements.
The environmental impact therefore depends heavily on the specific blockchain.
Regulation
Cryptocurrency and blockchain-related regulations vary by country and can change over time.
Businesses need to consider legal, tax, privacy, and compliance requirements before implementing blockchain systems.
Is Blockchain Worth Learning?
If you’re interested in cryptocurrency, software development, cybersecurity, fintech, Web3, or emerging technology, blockchain is worth understanding.
You don’t have to become a blockchain developer immediately.
Start with the fundamentals:
- Understand blocks and transactions.
- Learn what hashing does.
- Understand public and private keys.
- Learn how wallets work.
- Study Proof of Work and Proof of Stake.
- Explore transactions using a blockchain explorer.
- Learn the basics of smart contracts.
- Only then move into more advanced development or investment topics.
If you eventually want to develop blockchain applications, you can explore technologies such as Solidity, Ethereum development tools, JavaScript/TypeScript, and blockchain APIs.
The important thing is not to rush.
Blockchain combines computer science, cryptography, economics, networking, and software development. Understanding the basic pieces first makes the advanced material much easier.
Final Thoughts
Blockchain technology sounds complicated because it combines several technical ideas into one system. Once you separate those ideas—transactions, cryptographic signatures, hashes, blocks, nodes, and consensus—the concept becomes much easier to understand.
The biggest lesson I would give a beginner is to learn the technology before getting caught up in cryptocurrency prices or hype.
Open a blockchain explorer. Look at an actual transaction. Follow it into a block. Learn why it was accepted by the network. Then explore how different blockchain networks solve the same basic problems in different ways.
You don’t need to become an expert overnight. A basic understanding of how blockchain records and verifies information is already useful, especially as the technology continues to appear in finance, software, digital ownership, and business systems.